A Legal Guide to Acquisition Finance: Structuring and Navigating Business Transactions

A Legal Guide to Acquisition Finance: Structuring and Navigating Business Transactions

By: Gregory Prekupec and Rahul Gupta 

Key Takeaways

Acquisition financing enables businesses to fund acquisitions through debt, equity, or a combination of both, each with distinct risks and benefits. The choice between asset acquisitions, share acquisitions, or amalgamations depends on factors like tax implications, liability risks, and regulatory requirements. Successful acquisition financing requires careful structuring, due diligence, and alignment of financing with business growth objectives.

Introduction

    1. Acquiring a business is a significant milestone, often requiring substantial financial investment. Acquisition financing is a crucial component of this process, providing businesses with the necessary funding to acquire another company.

    1. This guide explores the key aspects of acquisition finance, including types of acquisitions, financing methods, and the unique factors that businesses must consider when structuring such deals.

Understanding Acquisition Finance

    1. Acquisition finance refers to the funding used to purchase a business. This financing can come from debt, equity, or a combination of both. Businesses seeking to acquire another company must carefully evaluate the financial structure that best aligns with their goals, risk tolerance, and long-term growth strategies.

    1. While debt financing typically allows businesses to leverage capital without diluting ownership, equity financing often provides long-term stability without immediate repayment obligations.

Types of Acquisitions

1. There are three primary methods of acquiring a business:

    • Asset Acquisition: The buyer purchases specific assets and liabilities of the target company. This method allows the buyer to select valuable assets while avoiding unwanted liabilities.

    • Share Acquisition: The buyer purchases all outstanding shares of the target company, effectively taking control of all assets and liabilities.

    • Amalgamation: Two companies merge to form a single entity, consolidating their operations, assets, and liabilities.

2. Each method has its advantages and challenges. Asset acquisitions provide flexibility in selecting valuable assets, while share acquisitions ensure full control of the target company. Amalgamations, on the other hand, create synergy by combining resources and expertise.

Choosing the Right Acquisition Method

    1. Several factors influence the selection of an acquisition method, including tax implications, liability issues, regulatory requirements, and the complexity of transferring ownership.

    1. Share acquisitions are generally simpler and require fewer contract assignments, whereas asset acquisitions minimize liability risks but involve additional documentation and third-party consents. Notwithstanding the foregoing, share transactions may require third-party consents to the change of beneficial ownership of the target.

Methods of Financing Acquisitions

Businesses can finance acquisitions through equity financing, debt financing, or a combination of both.

    1. Equity Financing: Involves raising capital by issuing shares or bringing in investors. This approach avoids debt obligations but dilutes ownership.

    1. Debt Financing: Involves borrowing funds from banks or financial institutions. Debt financing can be structured as senior debt, subordinated debt, or mezzanine financing, each with varying levels of risk and interest rates.

    1. Hybrid Financing: A combination of debt and equity, balancing financial leverage while maintaining some degree of ownership control.

Types of Loans Used in Acquisition Financing 

Several loan structures exist to finance acquisitions:

    1. Leveraged Loans: Used for high-risk acquisitions, often carrying higher interest rates.

    1. Asset-Based Loans (ABL): Secured against company assets, providing lenders with collateral.

    1. Investment-Grade Loans: Offered to highly-rated borrowers with lower risk profiles.

    1. Syndication//Bilateral Loans: Loans can be bilateral (single lender) or syndicated (multiple lenders), secured or unsecured, and structured to meet the specific needs of the transaction.

Key Steps in Financing an Acquisition 

Acquisition financing involves multiple steps, including:

    1. Private Sale or Auction: The target company may be acquired through a private negotiation or a competitive auction process.

    1. Loan Structuring: The buyer arranges financing through a lead lender, negotiating terms, interest rates, and repayment structures.

    1. Due Diligence: Buyers and lenders conduct thorough financial and legal assessments of the target company to mitigate risks. Lenders must be satisfied through their due diligence before funding.

    1. Purchase Agreement Execution: The final contract is signed, detailing the terms and conditions of the transaction. Lenders may require a signed purchase agreement in advance of the closing date to review, among other reasons, the material adverse change clause, to ensure the target is more-or-less the same as it was during the due diligence process.

    1. Closing and Fund Transfer: Once all conditions are met, funds are transferred, and the acquisition is completed.

Factors Unique to Acquisition Financing 

Acquisition financing presents unique challenges that businesses must address:

    1. Timing: The acquisition and financing transactions must close simultaneously to ensure a smooth transfer of ownership. Acquisition timing may become further complicated for practitioners if there are corresponding or simultaneous tax-deferred roll-over transaction(s), a franchise acquisition, or lease considerations, among others.

    1. Conditionality: Lenders may impose conditions such as financial covenants, due diligence requirements, and minimum equity contributions.

    1. Existing Debt Management: The target company’s existing debt must be reviewed, restructured, or repaid as part of the financing process.

    1. Security and Guarantees: Lenders often require collateral security, guarantees from the acquiring company, or pledges on the target’s assets.

Conclusion

By strategically navigating the financing landscape, companies can successfully execute acquisitions and position themselves for future growth.

Acquisition finance is a complex but essential tool for business growth and expansion. Understanding the available financing options, structuring the right deal, and managing the risks involved are critical to a successful acquisition.

Whether through debt, equity, or a combination of both, businesses must carefully evaluate their financing strategy to ensure long-term sustainability and value creation.
A Legal Guide to Acquisition Finance: Structuring and Navigating Business Transactions

A Mortgage Investment Corporation:- Key Elements

By: Gregory M. Prekupec and Rutendo Muchinguri


A Mortgage Investment Corporation (“MIC”) is defined in the Income Tax Act[1] as a form of a company that has the following key characteristics:

  • Must be a Canadian corporation, either federal or provincial;
  • Its only undertaking is the investing of funds of the corporation;
  • It does not manage or develop any real estate;
  • Has a minimum of 20 Shareholders; and
  • Is tax exempt.

MICs provide an alternative to residential financing outside of traditional financial institutions such as banks and credit unions for individuals who are either self-employed or who cannot qualify for traditional financing. As a result, MICs offer higher risk yet high yield investment.

Typically, the MIC will have a Manager or Administrator, who can be an individual or an entity who is responsible for providing management services of the MIC’s investment portfolio in exchange for management fees. Shareholders of the MIC buy into the share capital of the MIC in exchange for dividends. An MIC is recognised as a “flow through entity” which means that it must pay out all its income as dividends to Shareholders to maintain its tax exemption status.

Depending on how the MIC intends to raise capital, there may be a requirement to register with the Ontario Securities Commission if the MIC publicly offers its shares to the public. In this event, the MIC must register as a reporting issuer with the OSC and go through the prospectus filing process. Alternatively, the MIC may be exempted from the OSC registration requirement if it falls under any one of the prospectus exemptions – accredited investor exemption; offering memorandum exemption or private issuer exemption.

In Ontario, if an MIC directly arranges or sells mortgages in Ontario it must have a  mortgage brokerage licence issued by the Financial Services Regulatory Authority of Ontario. Alternatively, the Manager of the MIC can directly sell mortgages on behalf of the MIC which removes the need for the MIC to need this licence. An MIC that actively solicits investments from the public may need to register as an exempt market dealer with the OSC. Many MICs work with entities that are already registered as exempt market dealer.

MICs provide fairly flexible alternative financing and present interesting challenges for compliance to legal and accounting professionals alike.

[1] Section 130.1 of the Income Tax Act.

A Legal Guide to Acquisition Finance: Structuring and Navigating Business Transactions

Asset vs. Share Deals – A Taxing Decision (But We’ll Make It Less Painful)

By: Gregory Prekupec and Rahul Gupta 

Understanding the Tax Implications of Asset Vs. Share Deals 

When buying or selling a business, one of the most critical decisions is whether to structure the transaction as an asset sale or a share sale. Each approach has distinct tax consequences for both buyers and sellers. Understanding these implications can help businesses maximize tax efficiencies and avoid unexpected liabilities.

Seller Considerations: Why Share Sales Are Often Preferred

  1. From a tax perspective, sellers typically prefer selling shares rather than assets. The reason is simple: capital gains taxation. Under Canada’s capital gains tax regime, only 50% of a capital gain is taxable. Additionally, individual sellers may be eligible for the Lifetime Capital Gains Exemption (LCGE), which allows them to shelter $1,250,000.00 of capital gains on the sale of shares in a qualified small business corporation.
  2. By contrast, selling assets can lead to a higher tax burden. Some proceeds may be fully included in income, and if the business distributes these proceeds to shareholders, further tax can apply. This results in double taxation: once at the corporate level and again when the funds are distributed to shareholders.
  3. Another challenge with asset sales is the potential recapture of previously claimed depreciation, which is fully taxable. This can result in a significantly higher tax liability for the seller than if they had sold shares instead.

Buyer Considerations: Why Asset Purchases are Often Preferred

  1. Buyers typically prefer acquiring assets rather than shares because it provides them with greater tax benefits and flexibility. In an asset sale:
    • The buyer gets a stepped-up tax cost on the acquired assets, allowing for greater future tax deductions through capital cost allowance (depreciation).
    • The buyer can select which assets to acquire and avoid unwanted liabilities, which may not be possible in a share sale where all assets and liabilities transfer with the company.
    • However, buyers must consider additional costs such as sales tax and land transfer tax, which may apply to asset purchases but not share purchases.

2. One scenario where a buyer may prefer a share purchase is when the company being acquired has favourable tax attributes, such as non-capital losses, that the buyer can use to reduce taxable income post-acquisition. Additionally, purchasing shares may allow a buyer to preserve valuable contracts, licenses, or regulatory approvals, which might not be easily transferable in an asset deal.

Key Tax Considerations in Asset Purchases

1. If a business is sold as an asset sale, different tax rules apply to various types of assets:

  • Accounts Receivable: If the buyer and seller elect under ITA Section 22, the seller can claim a loss for bad debts, and the buyer can deduct uncollected amounts as income losses.
  • Inventory: Gains on inventory are taxed as ordinary income, not capital gains, which is less favourable for the seller.
  • Capital Property (e.g., land, buildings, equipment): Capital gains apply, with only 50% of the gain being taxable. For depreciable assets, there may also be recaptured depreciation, which is fully taxable.
  • Intangible Assets (e.g., goodwill, trademarks, customer lists): These assets are now included under Class 14.1 for tax purposes, allowing for a capital cost allowance of 5% annually.

        Key Tax Considerations in Share Purchases

        1. When a company is sold as a share sale, tax planning strategies can optimize the seller’s position, including:
        • Utilizing the Lifetime Capital Gains Exemption (LCGE) to shelter up to $1,250,000.00 of capital gains.
        • Safe Income Planning, where dividends are structured to reduce taxable capital gains.
        • Capital Dividends, which can be paid tax-free to shareholders in certain cases.

            Purchase Price Allocation: A Critical Favour

            1. One often overlooked aspect of business transactions is how the purchase price is allocated among the various assets being acquired. This allocation has major tax implications for both buyers and sellers. Sellers typically prefer to allocate more value to capital property to take advantage of lower capital gains tax rates, while buyers favour allocations that maximize future deductions (e.g., depreciable assets with high capital cost allowance rates).
            2. The Canada Revenue Agency (CRA) requires that the allocation be reasonable, so careful planning is necessary to avoid disputes.

              Other Important Tax Considerations

              1. Beyond the primary tax issues, several additional considerations can impact business transactions:
              • GST/HST Implications: While share sales are generally not subject to GST/HST, asset sales can be. However, an election under Excise Tax Act Section 167 can often eliminate GST/HST on the sale of a business’s assets.
              • Earn-Out Arrangements: If part of the purchase price is based on future business performance, the seller may need to carefully structure the agreement to avoid unexpected income tax consequences.
              • Non-Resident Sellers: If a non-resident is selling taxable Canadian property, the buyer may be required to withhold and remit tax to the CRA unless the seller obtains a clearance certificate under ITA Section 116.

                Final Thoughts

                1. Structuring a business sale as an asset or share deal requires careful tax planning. Sellers typically prefer share sales due to capital gains advantages, while buyers often favour asset purchases for tax efficiency and liability control. However, there are exceptions where share purchases can be advantageous for buyers, such as when acquiring valuable tax attributes.
                2. Given the complexity of tax laws and the financial implications involved, seeking professional legal and tax advice is essential. Our firm specializes in guiding businesses through corporate transactions, ensuring the best outcomes for all parties involved. Contact us today to discuss your business transition strategy and how we can help you navigate these important decisions.

                  A Legal Guide to Acquisition Finance: Structuring and Navigating Business Transactions

                  A Quick Guide for Managing Transactional Risk

                  By: Gregory Prekupec and Rahul Gupta 

                  Introduction

                  When drafting commercial agreements, it’s crucial to consider how risk is allocated between the parties to ensure your client’s interests are protected and that they don’t fall victim to outdated or unexamined precedents. A strong understanding of risk allocation allows lawyers to clearly articulate their clients’ post-closing obligations and potential liabilities.

                  Key Methods of Risk Allocation

                  Risk allocation in commercial contracts can take many forms. Below is a non-exhaustive list of common mechanisms:

                  • Indemnification
                  • Limitations on Liability
                  • Termination Rights
                  • Force Majeure
                  • Contractual Remedies
                  • Product Conditions & Warranties
                  • Insurance Coverage
                  • Payment Terms
                  • Guarantees

                  Now, let’s break down these risk allocation tools in more detail.

                  Indemnification

                  Definition: An indemnity clause requires one party to compensate the other for specific costs or liabilities, such as lawsuits, damages, or legal fees. This is often paired with a duty to defend and a hold-harmless obligation.

                  Purpose: A well-drafted indemnity clause can:

                  • Shift financial burdens onto the indemnifying party.
                  • Cover expenses not protected under common law (e.g., legal fees).
                  • Minimize uncertainty regarding future liabilities.
                  • Reduce litigation risks.
                  • Handle third-party claims effectively.

                  Enforcement: Courts generally enforce indemnity clauses unless they are deemed unreasonable or unconscionable (e.g., due to vague language, significant bargaining power disparities, or absurd results).

                  However, practical issues such as jurisdictional enforcement (i.e., enforcing a judgment in a foreign jurisdiction) and prolonged litigation can affect their utility.

                  Best Practices:

                  • Scope: Who is indemnified? (e.g., shareholders, employees, affiliates, capital providers)
                  • Nexus Language: What events trigger indemnification? (e.g., are the events “related to,” “caused by,” or “solely resulting from”?)
                  • Recoverable Damages: Define whether indemnification includes only incurred costs or also future/unpaid expenses.
                  • Exceptions: Consider excluding indemnification for gross negligence, willful misconduct, or failure to mitigate damages.
                  • Limitations: Use minimal thresholds, upward caps, and time limits to control exposure.
                  • Procedures: Specify the notice period, control the indemnifying party has over the litigation, and required cooperation of the indemnified party.

                  Limitations on Liability (“LL”) Clauses

                  Definition: LL clauses define and limit a party’s exposure under a contract.

                  Purpose:

                  • Capping damages (e.g., a multiple of fees paid under the contract).
                  • Excluding liability for indirect, consequential, or punitive damages.
                  • Avoiding application of tort-based remedies.

                  Enforcement: Courts generally uphold LL clauses if they are:

                  • Clear and specific (ambiguous language can be interpreted against the obligor).
                  • Explicit about covered and excluded liabilities (e.g., negligence).

                  Best Practices:

                  • Ensure the LL clause aligns with the indemnification provisions.
                  • Consider carve-outs for fraud, gross negligence, or intentional misconduct.
                  • Avoid conflicts with any “cumulative remedies” provisions.

                  Termination Rights

                  Definition and Categories: Termination Rights allow a party to end a commercial agreement. There are two types of termination rights:

                  1. Termination for Cause: Allows a party to end the contract due to specific breaches (e.g., non-payment, insolvency).
                  2. Termination for Convenience: Enables a party to exit the contract without cause (often requires notice, transition cooperation, or termination fees).

                  Considerations:

                  • Negotiation Power: Unilateral termination rights create leverage for a party and increases pressure on the counterparty.
                  • Consequences of Termination: Define penalties, required transition periods, and other obligations upon exit.

                  Force Majeure (“FM”)

                  Definition: “Superior force” in French.

                  Purpose: Allows a party to be excused from their contractual obligations if certain events occur which are negotiated to be beyond that party’s control (e.g., COVID-19, health emergencies, natural disasters, wars, civil unrest).

                  Best Practices:

                  • Events not covered by the FM clause will not be deemed as such. Specificity and intentionally are key to drafting effective FM clauses.
                  • A party should be able to terminate the agreement of disruptions over an FM event continue over a certain period of time.
                  • Prescribe which obligations remain despite any such termination (e.g., confidentiality)

                  Contractual Remedies

                  Definition and Categories: A list of contractually available reliefs to a party in a commercial agreement. There are four types:

                  • Equitable Remedies: Courts may order specific performance, injunctions, or rectification.
                  • Cumulative Remedies: Allows parties to pursue all available remedies beyond the contract.
                  • Exclusive Remedies: Limits remedies to those explicitly listed in the contract.
                  • Liquidated Damages: Pre-determined penalties for breaches. They are useful when damages are difficult to quantify.

                  Purpose: To create greater certainty by either expanding or minimizing the level of liability as a result of a breach of the agreement.

                  Best Practices:

                  • Ensure cumulative and exclusive remedies provisions don’t conflict.
                  • Confirm liquidated damages are compensatory and not punitive.
                  • Consider prohibiting or permitting equitable relief based on the circumstances of all parties.

                  Product Conditions & Warranties

                  Definition: Provincial laws provide for implied warranties on the sale of goods within the actual agreement. Parties to such agreements can manage risk by subscribing to or contracting out of these implied warranties.

                  Best Practices:

                  • Clearly state whether implied warranties apply or are excluded.
                  • Define the scope of express warranties to avoid unintended liabilities.

                  Insurance

                  Definition and Purpose: Parties can manage risk by negotiating for certain insurance requirements to ensure either party has the monetary capability to comply with its commercial obligations under an agreement.

                  Best Practices:

                  • Assess the need for additional insurance before mandating coverage. Do internal resources provide enough protection for ensuring contractual compliance?
                  • Ensure insurance aligns with indemnification obligations.

                  Payment Terms

                  Definition and Categories: The timing of when payment is required for the goods or services being contracted for can help to manage risk. There are two types:

                  • Deferred Payments: Favourable to buyers but risky for sellers.
                  • Advance Payments: Reduce seller risk but may require concessions to the buyer.

                  Best Practices:

                  • Define triggers for payment acceleration or deferral.
                  • Include late-payment penalties or early-payment discounts.

                  Guarantee

                  Definition: Guarantees are used to ensure payment or performance will be made on time by requiring a separate entity (e.g., the directors of a party, the parent corporation, etc.) guarantee or ensure the same.

                  Purpose: The inclusion of a third-party increases the chances that the counterparty will receive payment on time or performance.

                  Best Practices:

                  • Scope of Guarantee: Define if it is full or limited.
                  • Enforceability: Ensure the guarantor has the means to fulfill obligations.
                  • Exclusions & Expiry: Define conditions for termination of the guarantee.

                  A Legal Guide to Acquisition Finance: Structuring and Navigating Business Transactions

                  Franchise Law and Intellectual Property Law in Canada

                  By: Gregory M. Prekupec and Rutendo Muchinguri


                  The legal concept of a franchise focuses on two key aspects: there must be a granting of rights by a Franchisor to a Franchisee to operate a business, and there must be a corresponding payment by the Franchisee to the Franchisor for the granting of such rights. Rights that are granted are, amongst other things, usually associated with a trademark, tradename, symbol, or logo that is owned or licenced by the Franchisor. It is at this point that Franchise Law and Intellectual Property (“IP”) Law intersect.

                  In Ontario, the Arthur Wishart Act (“AWA”)[1] states that a Franchisor has an obligation to provide a franchise disclosure document (“FDD”) that discloses all material facts to the Franchisee in terms of Section 5 of the AWA. Section 1 of the AWA defines material facts as any information about the business, operations or control of the Franchisor, or the franchise system that would be reasonably expected to have a significant effect on the value or price of the franchise to be granted. The franchise system includes the use or association with a trademark, a logo or a trade name.[2]

                  A general rule of common law that one cannot grant rights they do not own or have the right to grant.[3] It follows therefore, that before a Franchisor can grant any rights to the Franchisee, they must have the legal right to do so. At this point, IP Law, due to its close relation to Trademarks, becomes relevant in assessing whether potential Franchisors actually hold the rights required to grant them to the Franchisee. If the Franchisor has a registered or unregistered a trademark as part of its franchise system and the Franchisor intends to grant such rights as part of the FDD, it is crucial that the registration or recognition of the trademark, symbol, or logo be confirmed and indisputable as understood in the Trademarks Act.[4]

                  If there is no prior review of the Franchisor’s IP, particularly if it is an unregistered trademark, there are legal and financial risks to the Franchisor:

                  • If the Franchisor decides to register the tradename or trademark and there are any issues with the Franchisor’s chosen trademark/name or logo in future, this may mean that the Franchisor cannot grant its intended trademark/name to the Franchisee, as this may be regarded as a material change as understood in the AWA. In this event, the Franchisor must provide a written statement of material change to the potential Franchisee as soon as this change occurs, before the FDD is signed or any payment has been made[5].
                  • If the Franchisor fails to disclose the status of the trademarks/name or provide a written statement of material change, the Franchisee has the right to rescind the franchise agreement for lack of or improper disclosure without any penalty or obligations. The repercussions of rescission are severe on the Franchisor – the Franchisor must refund any money received from the Franchisee, including the Franchise Fee, re-purchase all inventory from the Franchisee, and compensate the Franchisee for any losses incurred.[6]
                  • If a dispute arises with regard to the IP rights of the Franchisor, the Franchisor has a legal obligation to disclose this dispute to other potential Franchisees in its FDD package – thus eroding the goodwill of the Franchisor’s brand.

                  It is no coincidence that the IP and Franchise departments in a law firm usually work closely – the two areas of law are, indeed, two complimentary peas in a pod. An IP review of the franchise system prior to the preparation of the FDD is therefore crucial – proceeding without such a review can have adverse consequences on the Franchisor and its business and result in non-compliance with the AWA and financial ruin.

                  [1] Arthur Wishart Act (Franchise Disclosure), 2000 S.O. 2000, c3.

                  [2] Section 1 of the AWA.

                  [3] Nemo dat quod non habet.

                  [4] Trademarks Act, RSC 1985, c T-13.

                  [5] Section 5 of the AWA.

                  [6] Section 6(6) of the AWA.

                  A Legal Guide to Acquisition Finance: Structuring and Navigating Business Transactions

                  BioSteel left “unquenched” in quest for injunction before Ontario Court

                  “May Cheng, Nicolas Auger

                  In a recent Ontario Court decision, BioSteel Inc. v. Cizzle Brands Ltd., 2024 ONSC 5515, Justice Parghi denied BioSteel Inc. and DC Holdings (“BioSteel”) an interlocutory injunction to stop Cizzle Brands Ltd. and Cizzle Brands Inc. (“Cizzle”) from using similar packaging for its sports hydration drinks. This ruling, released on October 18, 2024, following an August hearing, underscores important nuances in intellectual property law and the challenges brands face in protecting their trade dress.

                  Background: BioSteel’s Unsuccessful Bid to Block Cizzle’s Competing Product

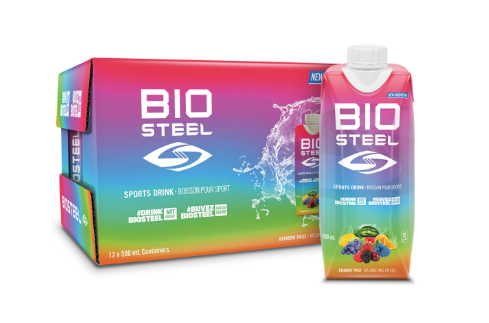
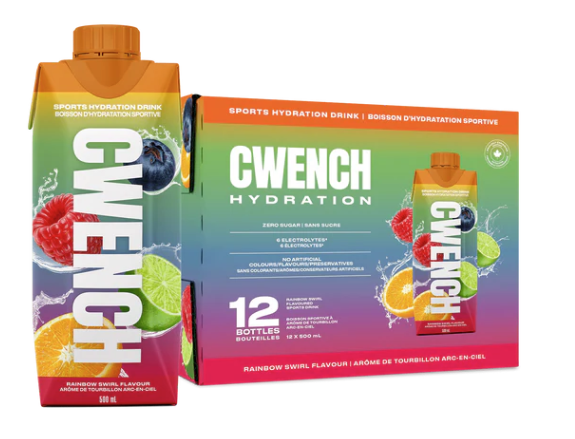
                  The conflict began after BioSteel entered creditor protection under the Companies’ Creditors Arrangement Act (CCAA) in September 2023. DC Holdings emerged as the successful bidder for BioSteel’s assets, including the intellectual property associated with its popular sports hydration drinks. Former BioSteel executive, Mr. Celenza, subsequently launched a rival hydration brand, Cizzle, alongside other former BioSteel team members. Cizzle’s new line of CWENCH drinks debuted in May 2024, sporting vibrant packaging that closely resembled BioSteel’s established look, albeit with the distinct CWENCH brand name.

                  These visual similarities drove BioSteel to seek an injunction, arguing that Cizzle’s packaging could confuse consumers and harm BioSteel’s market share and brand reputation. Yet, despite these apparent likenesses, the court ruled against granting the injunction.

                  BioSteel Sports Drink Rainbow Twist 12 Pack in Canada


                  BioSteel Sports Drink in Rainbow Twist, 12 Pack

                  “Image courtesy of BioSteel Canada. Available at BioSteel – Canada

                  CWENCH Sports Drink Rainbow Swirl in Canada


                  CWENCH Sports Drink in Rainbow Swirl

                  “Image courtesy of CWENCH Hydration. Available at CWENCH Hydration – Canada

                  Legal Analysis: Why BioSteel’s Injunction Was Denied

                  At the heart of the decision lies the three-prong RJR Macdonald test, used to assess injunction requests. Here’s how the court applied each prong:

                  1. Strong Prima Facie Case
                    BioSteel’s bid for an injunction faltered on the first prong, an unusual outcome in such cases. Justice Parghi concluded that BioSteel had not demonstrated a “strong prima facie case” or even a “serious issue to be tried” under the tort of passing-off. Typically, injunctions are denied at the second stage of the test, where the difficulty often lies in proving “irreparable harm.” However, the judge was not convinced that BioSteel’s brand recognition extended beyond its trademark to encompass the specific “get-up” or trade dress of its packaging.
                  2. Goodwill and Brand Association
                    While BioSteel argued that its packaging was synonymous with its brand goodwill, Justice Parghi found insufficient evidence linking the packaging design to BioSteel’s market reputation independently of its BIOSTEEL trademark. This absence of compelling evidence weakened BioSteel’s claim that Cizzle’s CWENCH packaging misrepresented their brand, thus failing to establish a case of passing-off.
                  3. Impact of Injunction Denial
                    As a result of the court’s decision, Cizzle may continue marketing its CWENCH drinks in their current packaging until trial. BioSteel still has the opportunity to present additional evidence at trial and may consider appealing the injunction denial. In the meantime, the competitive landscape remains unaltered, with both brands contending for market share in the hydration drinks sector.

                  Implications for Brand Protection and Trade Dress Claims

                  The BioSteel Inc. v. Cizzle Brands Ltd. decision highlights the complexities brands face in securing legal protection for trade dress elements, such as packaging design. The case underscores the need for clear evidence linking trade dress to brand goodwill, separate from trademark recognition. Brands pursuing passing-off claims may benefit from extensive consumer perception data that illustrates a direct association between trade dress and brand identity.

                  As the broader litigation continues, BioSteel must build a stronger evidentiary foundation if it hopes to successfully claim trade dress infringement. For now, the court’s decision offers a cautionary tale: securing an injunction based on trade dress requires more than surface-level similarities—it demands a compelling argument supported by evidence that consumers unmistakably associate the trade dress with the brand’s goodwill.

                  Skip to content